


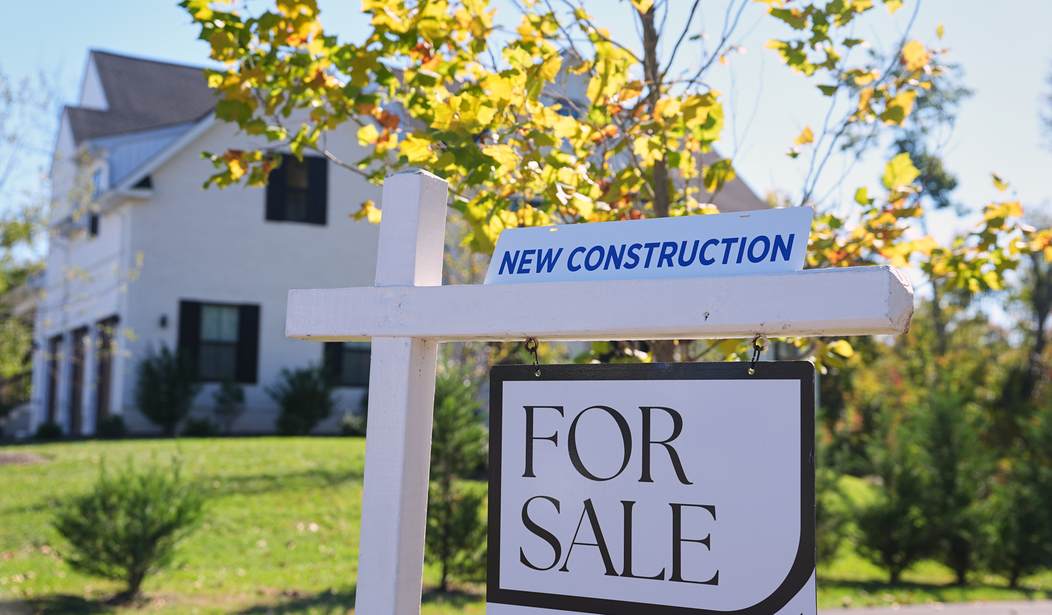
We are getting close to Halloween, and the Trump administration is being haunted by a creepy idea that survived the Biden years. Inflation will get worse if a spooky idea on housing affordability is adopted by Trump bureaucrats. Like Freddy Krueger, the monster from A Nightmare on Elm Street, or the demonic clown, Pennywise from the movie IT, this terrifying idea is hard to escape.
Inflation impacts the affordability of everyday items people need, like gas, groceries, and housing. The administration should be working on novel ways to address these concerns; however, a stale idea of the Biden administration seems to have survived and is threatening potential new homeowners. This is a policy which would weaken credit standards and would end up making mortgages more expensive. This is a liberal idea resurrected from the political dead.
The tri-merge credit model, which is the current standard, uses data from three reputable nationwide credit agencies. This system has been in place for years and has proven to be a stable, workable standard for the underwriting of mortgages. Having a comprehensive view provides the lender with an accurate estimation of the consumer’s risk in taking on a mortgage for a new home. This allows the three competing credit agencies to provide a balanced view of an applicant and one that has three different analyses of the potential mortgage holder. Having three different agencies also prevents concentration of influence in one agency, which could skew the view of the lender and provide an easier road for risky mortgages.
The Biden administration wanted to fast track risky mortgages to provide a sugar high to the housing market. Under President Biden, the Federal Housing Finance Agency (FHFA) considered a new system that allowed alternative credit reporting, including something called the bi-merge model. This would streamline the reports needed from three to two (or even one) credit agencies, and this could pose a real risk to the market as a whole.
The Director of the FHFA, Bill Pulte, has supported the idea of a tri-merge model in the past, but there are indications there is openness at the FHFA to a more flexible model favored by progressives. Bloomberg reported on October 1, 2026, “the Federal Housing Finance Agency is planning to direct Fannie Mae and Freddie Mac within weeks to require lenders to pull credit data from two major credit reporting bureaus instead of three, according to a person familiar with the plans.” This announcement could come as soon as October 12, 2026, and would prove to be a big mistake for the Trump administration. Ditching the tri-merge model would insert unneeded risk into the mortgage market at a time when homeownership is a challenge. Allowing less creditworthy borrowers into the market will hike interest rates and push the new cost towards responsible potential mortgage holders.
The bi-merge model will hike interest rates at a time when Americans are struggling with already high rates, additional inflation, and less disposable income. It is simple economics to understand that when potential risk is inserted into the mortgage market, investors and lenders will want more resources to compensate them for the increased risk. These costs will lead to even higher interest rates on mortgage loans – even higher than the skyrocketing rates we are seeing today. Just a small hike in interest rates hits borrowers with thousands of dollars in interest over the life of a 30-year mortgage.
Progressive proponents of the bi-merge model argue that the savings in the short term would help mortgage seekers. The problem is that pulling a bi-merge report would save about $30 for the report's direct cost, yet it would have the impact of a massive cost on the back end when mortgage rates go up because of the increased risk in the system.
Of course, the big winners of a potential change are mortgage lenders themselves. Consumers are the ones hurt, but any idea that reduces costs for mortgage lenders is supported by the industry, because they issue the mortgages and then can hike interest rates for variable-rate mortgages
It is a common theme in Washington that the big lobbying interests usually prevail over the consumer. This idea to weaken credit standards falls right into the category of an idea that lowers costs for the mortgage industry and lobbyists while allowing them to charge more because of the increased probability of risky mortgage holders. Yet another win-win proposition for the banks, while homeowners end up paying the bills.
Editor’s Note: Do you enjoy Townhall’s conservative reporting that takes on the radical Left and woke media? Support our work so that we can continue to bring you the truth.
Join Townhall VIP and use promo code FIGHT to receive 60% off your membership.

Join the Conversation
VIP members get the ability to comment on articles.